
You're RNOR, not fully resident, if you meet any one of four conditions built around your recent years abroad and this year's days. While RNOR, income that both arises and is received outside India generally stays outside Indian tax, except income from a business controlled in India or a profession set up here. After a decade or more abroad, most people get two or three tax years of it, depending on when they return; frequent visitors get fewer, or none.
Is this you? This explainer assumes you're already resident in India for the tax year, and is about the next question: ordinarily resident, or RNOR? Not sure you're resident at all yet? Check your residency status first.
This assumes your residency status is Resident for the tax year, working out whether you're RNOR. Moving back this year? Check your residency status first, because the answer can change.
Part of our guide to moving back to India, this explainer covers one question: once you’re resident again, are you ordinarily resident, or RNOR — and if RNOR, for how long?
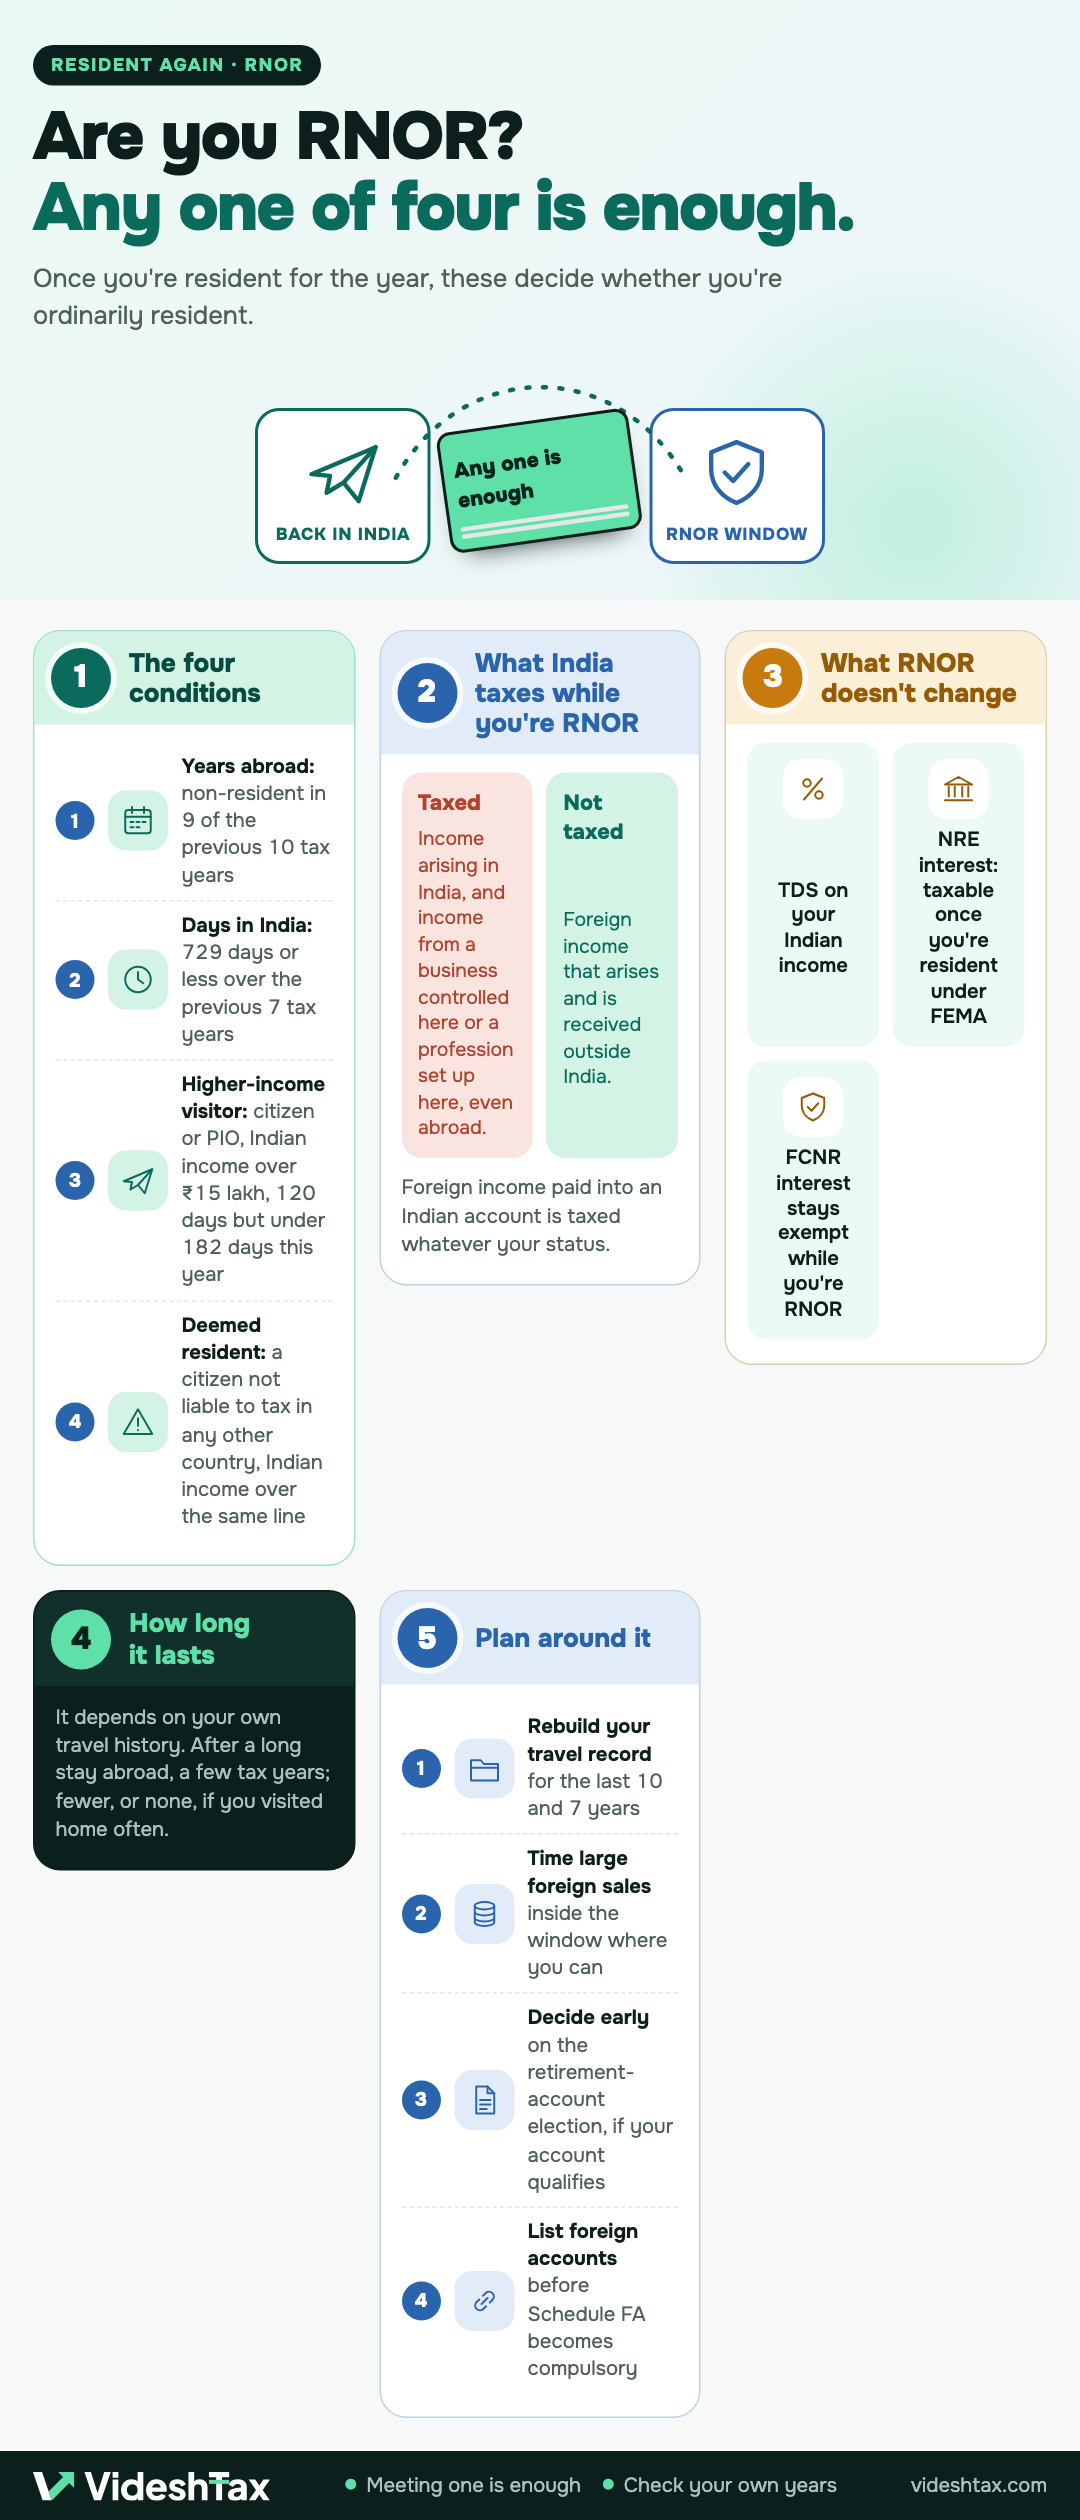
Once you're resident for the year, these decide whether you're ordinarily resident.
Years abroad: non-resident in 9 of the previous 10 tax years
Days in India: 729 days or less over the previous 7 tax years
Higher-income visitor: citizen or PIO, Indian income over ₹15 lakh, 120 days but under 182 days this year
Deemed resident: a citizen not liable to tax in any other country, Indian income over the same line
Foreign income paid into an Indian account is taxed whatever your status.
It depends on your own travel history. After a long stay abroad, a few tax years; fewer, or none, if you visited home often.
Rebuild your travel record for the last 10 and 7 years
Time large foreign sales inside the window where you can
Decide early on the retirement-account election, if your account qualifies
List foreign accounts before Schedule FA becomes compulsory
The exact conditions
Once you’re resident for a tax year — by the ordinary day tests, the higher-income route, or the deemed-resident rule — you’re RNOR rather than ordinarily resident if any one of four conditions is true 2025 Act s. 6(13)was s. 6(6):
- You were a non-resident in 9 or more of the previous 10 tax years; or
- You spent 729 days or less in India over the previous 7 tax years; or
- You’re a citizen or person of Indian origin with Indian income above ₹15 lakh who spent at least 120 days but fewer than 182 days in India this year. We read this as covering only someone made resident by the higher-income rule for visitors; the Act can be read more widely, so ask a CA if you live here, have that income and spend 120 to 181 days a year in India; or
- You’re a deemed resident: a citizen not liable to tax in any other country, with Indian income above the same threshold, treated as resident even without meeting either day test.
Meeting any one is enough. Most returning NRIs qualify through the first two, which is why they’re the ones worth understanding in detail. The third mostly catches a visiting citizen or person of Indian origin rather than someone who’s actually moved back, on our reading: see the 120-day rule for how that route works.
The fourth is rarer still for a returning reader, since it needs you not to be resident by days at all: the deemed-resident guide covers who it catches and why they end up RNOR too.
Where this comes from: old law, new numbering
Before the 2025 Act, this was section 6(6) of the 1961 Act, which set the first two tests; the Finance Act, 2020 added the higher-income and deemed-resident routes as new sub-clauses (c) and (d) of the same subsection. The old sub-clause (c) pointed expressly to the visitor rule, which is why we read the new one the same way. The 2025 Act sets all of them out as clauses (a), (b) and (c) of section 6(13), with the same substance.
The four-limb structure matters in practice because the routes are genuinely independent: failing one doesn’t rule out RNOR if you meet another. Someone who lived abroad continuously for six years might fail the first test (six years abroad is short of 9) but pass the second easily (barely any days in India over the lookback years), and either one alone is enough.
What’s taxed, and what isn’t, while you’re RNOR
RNOR sits between NRI and ordinarily resident on what India taxes, not on how you file. You file as a resident, and Indian income is taxed exactly as it would be for any resident. The difference is foreign income: income that arises outside India, and isn’t first received in India, is left out of your Indian total income while you’re RNOR, the same way it would be for an NRI 2025 Act s. 5was s. 5.
| Income | NRI | RNOR | Ordinarily resident |
|---|---|---|---|
| Rent, interest, salary or gains arising in India | Taxed | Taxed | Taxed |
| Foreign salary, foreign bank interest, foreign dividends, gains on foreign shares/funds, received abroad | Not taxed | Not taxed | Taxed, with credit for foreign tax |
| Income from a business controlled from India or a profession set up here, wherever earned | Taxed if it arises in India | Taxed, even if it arises abroad | Taxed |
| Schedule FA foreign-assets reporting | Not required | Not required | Required every year |
Foreign income that’s paid into an Indian account is taxed whatever your status.
The one carve-out is worth taking seriously precisely because it’s easy to miss: if you control a business from India, or you’ve set up a profession here, income it earns abroad is taxed even while you’re RNOR. It’s aimed at people who run something from an Indian base while keeping foreign income streams, not at ordinary foreign salary, dividends or interest, which stay outside the net. If you’re not sure whether something you’re involved in counts, get a CA’s view before you assume it’s protected.
Two things RNOR does not do, compared with being ordinarily resident: it doesn’t change TDS on Indian income, and it doesn’t touch your FEMA account status. Your NRE account still becomes taxable the day you’re resident under FEMA, RNOR or not; only FCNR interest specifically follows your RNOR years. NRE, NRO and FCNR accounts covers how each one is taxed.
How long the window lasts, in practice
There’s no single answer, because both routes look at your own travel history. These three show how differently it can play out for people who look similar on paper but lived abroad differently.
Ten years in Seattle, rarely visiting
Priyanka moves back to Bengaluru after ten years in Seattle, having gone home for only a couple of short visits a year. She was a non-resident in every year the checker looks at.
| Test | What the checker found | Met? |
|---|---|---|
| Days in India this year | You were in India for 280 days this tax year, which meets the test of 182 days or more. You're resident. | Yes |
| Years as a non-resident | You were a non-resident in 10 of the previous 10 tax years, which meets the test of 9. You're not ordinarily resident. | Yes |
| Days over the longer lookback | You spent 60 days in India over the previous 7 tax years: 729 days or less. You're not ordinarily resident. | Yes |
| Resident only through higher income | You weren't resident through the higher-income test, so that route to RNOR doesn't apply. | No |
India taxes your Indian income and anything received in India. Most foreign income earned and received abroad stays outside Indian tax, unless it comes from a business controlled in, or a profession set up in, India.
Priyanka clears the first test comfortably — she was a non-resident in every year of the lookback — and the second as well, since her visits added up to so little. Both routes agree, which is the common case for someone who left for good and travelled home rarely.
Six years in London, with a longer earlier stint at home
Arvind moves back to Chennai after six years in London. Before that he'd lived in India, so he was a non-resident in only six of the years the checker looks at, but his visits home since he left added up to little.
| Test | What the checker found | Met? |
|---|---|---|
| Days in India this year | You were in India for 200 days this tax year, which meets the test of 182 days or more. You're resident. | Yes |
| Years as a non-resident | You were a non-resident in 6 of the previous 10 tax years, fewer than 9. | No |
| Days over the longer lookback | You spent 450 days in India over the previous 7 tax years: 729 days or less. You're not ordinarily resident. | Yes |
| Resident only through higher income | You weren't resident through the higher-income test, so that route to RNOR doesn't apply. | No |
India taxes your Indian income and anything received in India. Most foreign income earned and received abroad stays outside Indian tax, unless it comes from a business controlled in, or a profession set up in, India.
Arvind fails the first test outright, but the second still carries him over, because his total days in India across the longer days-test window stayed low even though one of those years, the year he left, counted as a resident year. This is the case worth remembering: a shorter stint abroad doesn’t automatically mean no RNOR, if you kept your visits brief.
Frequent trips home from Dubai
Fatima moves back to Hyderabad after a career based in Dubai, but she travelled home often for family and business, spending a large part of most years in India.
| Test | What the checker found | Met? |
|---|---|---|
| Days in India this year | You were in India for 250 days this tax year, which meets the test of 182 days or more. You're resident. | Yes |
| Years as a non-resident | You were a non-resident in 3 of the previous 10 tax years, fewer than 9. | No |
| Days over the longer lookback | You spent 900 days in India over the previous 7 tax years, more than 729 days. | No |
| Resident only through higher income | You weren't resident through the higher-income test, so that route to RNOR doesn't apply. | No |
India can tax your worldwide income this year, including your salary abroad. You report foreign assets in your return and claim credit for tax paid abroad.
Fatima fails both tests: she wasn’t a non-resident in enough of the lookback years, and her days in India over the days-test window add up to far more than the limit. She’s resident and ordinarily resident from her first year back, with no RNOR window at all, even though she genuinely lived and worked abroad for years. This is the case people plan around least, and it’s the reason to check your own numbers rather than assume. Her Indian income is below ₹15 lakh, so the deemed-resident rule doesn’t reach her either.
For how many years your own history is likely to buy you, use the RNOR window planner.
How to plan around it
Because the window is set by history you’ve already made, not by anything you do after you land, planning happens on two sides: get the figures right, and use the time well.
Get the figures right first. Rebuild your travel record for the last several years before you rely on either test — passport stamps, employer records, or a travel-tracking app if you kept one. The two routes look at different lookback periods (the last 10 years for the first, the last 7 for the second), so you genuinely need both counts, not a rough guess.
Then use the window while it’s open. A large foreign disposal — shares, a house, vested employer stock — is taxed very differently depending on which side of the window it falls, so time it inside the window where you can, and weigh that against market timing and any tax the other country still charges on the same sale. A foreign retirement account benefits from the same thinking: decide early whether to elect deferred taxation on it 2025 Act s. 158was s. 89A, if the account is in a notified country and was opened while you lived there, since that decision is easiest to get right before your first return is due, not after. And start listing every foreign account and asset well before Schedule FA becomes compulsory, so the transition to ordinarily-resident filing isn’t a scramble.
The moving-back pillar’s first-three-years checklist ties the election together with the accounts and Schedule FA side.
Common mistakes
- Assuming RNOR lasts “two or three years” without checking your own figures. It depends on your travel history, and can be longer, shorter or absent.
- Treating RNOR as the same thing as NRI status. It isn’t: you file as a resident, and the business-controlled-from-India carve-out still applies.
- Forgetting that only one of the two main routes needs to be met. A weak result on one test doesn’t rule out RNOR if the other is met.
- Assuming FEMA and RNOR move together. Your NRE account’s tax exemption ends on FEMA residency, not on your RNOR status.
When to get a chartered accountant
Get one to rebuild and check your travel-history figures if you’re within a year or two of either threshold, to confirm whether foreign income you control counts as “business controlled from India”, and before timing a large foreign disposal around the edge of your window. If you’re also a US, UK or Canadian taxpayer, bring that country’s adviser into the same conversation, since your window and theirs rarely line up.
Next steps
Questions people ask
Do I have to apply for RNOR status?
No. There's no application or election. It follows automatically from your residency days this year and your travel history over the lookback years, the same way NRI and resident status do. You simply tick the right box in your return, and it's worth getting a CA to check the figures if you're close to any of the thresholds.
Can I be RNOR for more than two or three years?
Not if you live in India full-time. However long you were abroad, two full years here take you past 729 days, and the non-resident-years test fails in your third year back, so the window after a long stay abroad is at most three tax years, and two if you return in April. It's shorter, or absent, if you visited often. Only the higher-income 120-day route could run longer, and on our reading that covers visitors, not people who've moved back. The RNOR window planner shows your own years.
Is RNOR the same thing as being an NRI?
No, and mixing the two up is the most common mistake on this page. An NRI isn't resident at all, and only Indian income is taxed. RNOR is resident, files as a resident, and shows their status as such, but most foreign income is still left alone. Some rules that apply only to residents, not NRIs, do reach an RNOR taxpayer.
Does RNOR status affect my bank accounts?
Only indirectly. FEMA, not the RNOR test, decides when your NRE account stops being tax-exempt and when your accounts are re-designated: that happens once you're resident under FEMA, generally the day you come back to live in India, whether or not you turn out to be RNOR for tax that year. FCNR interest is the exception that follows RNOR specifically: it stays exempt for as long as you're RNOR. Our moving-back pillar covers the account side in full.
What counts as a 'business controlled from India'?
Broadly, a business whose real management and decisions sit in India, even if it earns money abroad — as opposed to a business you merely own a stake in from India, or ordinary foreign employment income, which stay outside this carve-out. It's a facts-and-circumstances question the department can look at closely, so get a CA's view if you run or control anything abroad while you're RNOR, rather than assuming it's automatically protected.
Sources
- Income-tax Act, 2025: s. 5 (scope of total income, the RNOR foreign-income carve-out) and s. 6(13) (not ordinarily resident), as gazettedegazette.gov.in
- Finance Act, 2020 (No. 12 of 2020), s. 4: inserting sub-clauses (c) and (d) into s. 6(6) of the Income-tax Act, 1961 (not ordinarily resident), as gazettedgstcouncil.gov.in
- Income Tax Department: Residential statusincometaxindia.gov.in
Update log
- First published.