
Most of the dates that matter to an NRI never make it onto one page. India and the country you live in run on different tax years, use different words for the same idea, and change their own rules on their own schedule. This page puts the two side by side: pick a tab below for India or the United States, and see what’s due, and when.
Everything on this page is for tax year 2026-27 in India, and for US tax year 2026, filed in 2027, plus the estimated-tax payments for 2027. Some of the year’s early dates have already passed; they stay on the page so you can check what was due. We’ll add tax year 2027-28 once it’s confirmed, and cover the UK, Canada, the UAE, Australia and Singapore here as their own deadline facts are checked — a country appears only once its dates are verified, never as a placeholder.
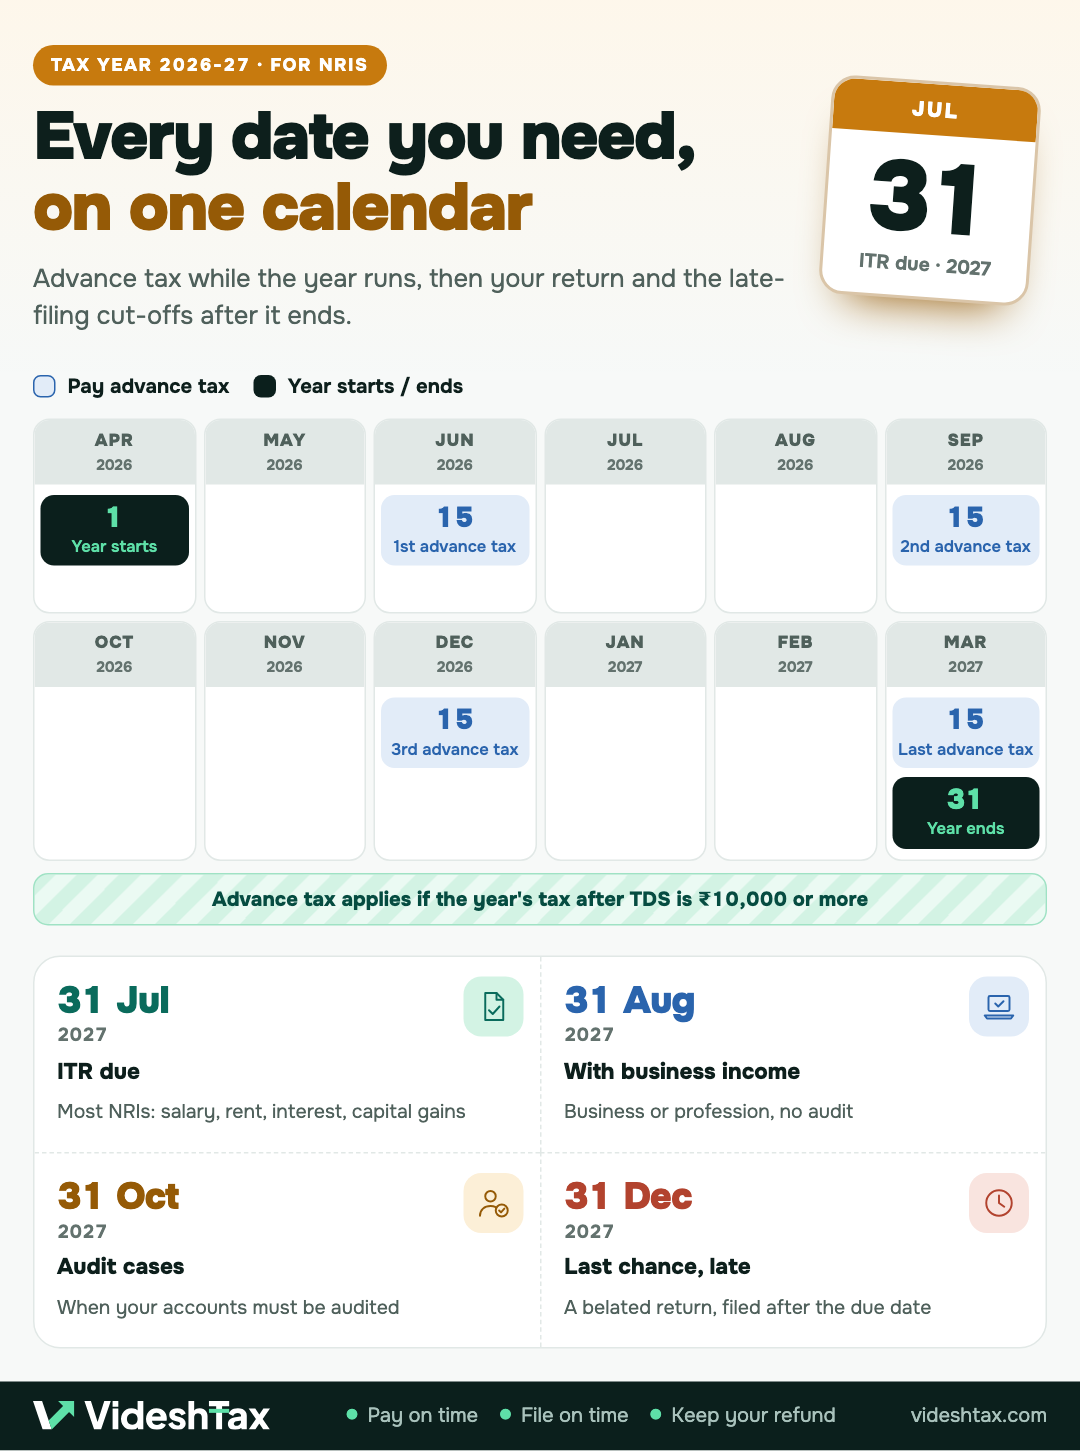
Advance tax while the year runs, then your return and the late-filing cut-offs after it ends.
- Pay advance tax
- Year starts / ends
- APR20261Year starts
- MAY2026
- JUN2026151st advance tax
- JUL2026
- AUG2026
- SEP2026152nd advance tax
- OCT2026
- NOV2026
- DEC2026153rd advance tax
- JAN2027
- FEB2027
- MAR202715Last advance tax31Year ends
Advance tax applies if the year's tax after TDS is ₹10,000 or more
Most NRIs: salary, rent, interest, capital gains
Business or profession, no audit
When your accounts must be audited
A belated return, filed after the due date
Why the dates aren’t typed in
Every deadline below renders from the same facts register that our guides and calculators read, through a register key you can see in the small print under each table. That matters for two reasons. First, a date here can never quietly drift from the same date quoted in a guide, because they’re the same number. Second, when a date changes — the government extends a filing deadline, or a new Finance Act moves one — updating the one fact updates this page, the guide that explains it, and any calculator that uses it, in a single edit.
What “India” covers
The India tab assumes you’re a non-resident for the whole of tax year 2026-27, filing an individual return with no exotic complications. It groups four kinds of date. Advance tax instalments are payments through the year on income the bank or a tenant doesn’t already deduct tax from, such as capital gains or business income; miss one and interest usually runs on the shortfall (a capital gain you couldn’t have foreseen is covered if you pay the tax in the next instalment). TDS certificates are what a bank or tenant must hand you each quarter, proving what they deducted — the paper trail you need before you can claim it back. Filing your return covers the ordinary due date, the later dates if you have business or professional income in India or your accounts need an audit, and the belated and revised-return windows if you miss the first one or need to correct it. The updated return is a much longer window, there specifically for declaring income you missed — it can’t be used to claim a bigger refund.
If any of this doesn’t quite fit your situation, start with do NRIs need to file at all.
Once you know you must file, which ITR form applies to you decides the rest of the paperwork.
And if most of your Indian income is NRO interest, the TDS-certificate dates below are the ones your bank owes you each quarter.
What “United States” covers
The US side assumes you file as a US citizen, green card holder or tax resident with a calendar-year return — the case for almost every US-based NRI. Tax Day is the regular due date; living outside the US on that day gives you an automatic two-month extension with no form, and a further extension to mid-October needs Form 4868, filed before the two-month date. Those extend the time to file, not the time to pay: interest runs on unpaid tax from the regular due date regardless. FBAR is a separate report, on foreign bank and investment accounts together above a threshold, with its own automatic extension that needs no request at all. Estimated tax is what a filer with income the withholding tables don’t reach — rental income, dividends, gains — pays in four instalments through the year, so a large one-off Indian sale doesn’t leave a US underpayment penalty waiting at filing time.
How tax treaties work for NRIs covers the credit each country gives for tax the other one keeps, so the same rupee isn’t taxed in full twice.
If Indian mutual funds are part of your year, the PFIC guide has its own filing date, tied to your regular return.
FBAR and FATCA reporting for Indian accounts goes through both reports and their thresholds in full.
Using the .ics files
Each tab has an “Add to your calendar” button that downloads one .ics file for that country, with
every date on this page as a day-long event, ready to import into Google Calendar, Outlook or Apple
Calendar. Re-download it after a Budget or Finance Act changes a date; the file doesn’t update
itself once it’s on your calendar.
None of these dates are advice for your own filing. A due date can move for a public holiday, a CBDT extension or an IRS announcement in ways this page won’t know about until we update the fact behind it. Where a specific date decides real money — an advance-tax instalment, a filing deadline close enough that a delay costs interest — confirm it with a CA or CPA before you rely on it.
Deadlines by country
Advance tax instalments
Due if your tax for the year, after TDS, comes to ₹10,000 or more.
| Deadline | Date | Source |
|---|---|---|
| 1st instalment | 15 June 2026 | Income-tax Act, 2025, s. 408(1) Table Sl. 1 |
| 2nd instalment | 15 September 2026 | Income-tax Act, 2025, s. 408(1) Table Sl. 2 |
| 3rd instalment | 15 December 2026 | Income-tax Act, 2025, s. 408(1) Table Sl. 3 |
| 4th and last instalment (the whole of the year's tax) | 15 March 2027 | Income-tax Act, 2025, s. 408(1) Table Sl. 4 |
TDS certificates for non-salary payments
When the payer must give you the certificate for tax deducted on interest or rent that quarter. A property sale to an individual buyer from 1 October 2026 follows a monthly timetable instead: see selling property in India.
Filing your return
Updated return
A later window to file or correct a return, only to declare more income — it can't create or increase a refund.
| Deadline | Date | Source |
|---|---|---|
| Updated return window closes | 31 March 2032 | Income-tax Act, 2025, s. 263(6)(a) ("within forty-eight months from the end of the financial year succeeding the relevant tax year") |
Figures for tax year 2026-27, checked 3 October 2026.
Filing your federal return
| Deadline | Date | Source |
|---|---|---|
| Regular due date (Tax Day) | April 15, 2027 | 26 U.S.C. §6072(a): individual returns due "on or before the 15th day of April following the close of the calendar year" |
| Automatic 2-month extension if you live outside the US | June 15, 2027 | IRS, 'U.S. Citizens and Resident Aliens Abroad': "on the regular due date of your return, you are allowed an automatic 2-month extension to file your return without requesting an extension" |
| Extended due date, with Form 4868, filed before the automatic 2-month date | October 15, 2027 | IRS, 'U.S. Citizens and Resident Aliens Abroad': "you can request an additional extension to October 15 by filing Form 4868" |
FBAR
| Deadline | Date | Source |
|---|---|---|
| FBAR due date | April 15, 2027 | FinCEN, FBAR Due Date Clarification (PD 02-02-2018) ("the annual due date for filing FBARs … is April 15"; follows the IRS weekend/holiday rule) |
| FBAR automatic extension (no request needed) | October 15, 2027 | FinCEN, FBAR Due Date Clarification (PD 02-02-2018) ("FinCEN will grant filers failing to meet the FBAR annual due date of April 15 an automatic extension to October 15 each year. Accordingly, specific requests for this extension are not required.") |
Estimated tax
Paid with Form 1040-ES or online, if withholding doesn't cover your tax.
| Deadline | Date | Source |
|---|---|---|
| Last 2026 instalment | January 15, 2027 | IRS, Form 1040-ES instructions: the fourth payment period falls on January 15 of the following year |
| 1st 2027 instalment | April 15, 2027 | 26 U.S.C. §6654(c)(2) (instalment due dates: 1st April 15 / 2nd June 15 / 3rd September 15 / 4th January 15 of the following taxable year), read with §7503 |
| 2nd 2027 instalment | June 15, 2027 | 26 U.S.C. §6654(c)(2) (instalment due dates: 1st April 15 / 2nd June 15 / 3rd September 15 / 4th January 15 of the following taxable year), read with §7503 |
| 3rd 2027 instalment | September 15, 2027 | 26 U.S.C. §6654(c)(2) (instalment due dates: 1st April 15 / 2nd June 15 / 3rd September 15 / 4th January 15 of the following taxable year), read with §7503 |
| Last 2027 instalment (the following January) | January 18, 2028 | 26 U.S.C. §6654(c)(2) (instalment due dates: 1st April 15 / 2nd June 15 / 3rd September 15 / 4th January 15 of the following taxable year), read with §7503 |
Figures for tax year 2026-27, checked 11 October 2026.
Only India and the US are covered so far. More countries are added here once their deadline facts are checked, never before.